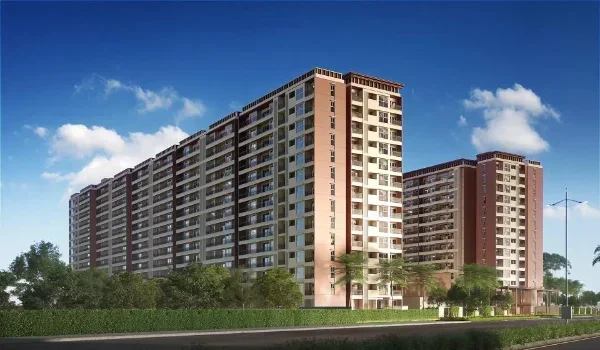
Prestige Falcon City Thane Payment Plan
Featured Image of Prestige Falcon City Thane Payment Plan


Prestige Falcon City Thane follows a construction-linked payment plan (CLP) with 10 equal instalments of 10% each. You pay 10% at booking and 10% when you sign the Agreement of Sale. The remaining 80% moves across eight construction milestones, ending with handover by December 2031.

For a 2 BHK priced from ₹1.62 Cr, each instalment works out to about ₹16.2 lakh. Since every payment follows real work on site, your money moves only as the towers rise. Below, you will find each stage, the extra costs outside the plan, and smart ways to fund it.
What Is the Payment Plan at Prestige Falcon City Thane?


The project uses a 10:10:80 construction-linked plan that ties most of your payments to site work. You pay 10% to book, 10% at the Agreement of Sale, and 80% in eight equal parts. The last 10% falls due at the Occupancy Certificate stage, just before handover.

Here is how the split looks in simple terms:

  • Booking amount of 10% locks your chosen unit and floor.
  • Agreement stage payment of 10% comes due when you sign and register the Agreement of Sale.
  • Construction payments of 80% follow eight milestones, from excavation to the Occupancy Certificate.

Stage-by-Stage Payment Schedule


The table below shows each milestone with the amount due for the starting price of each configuration. Actual figures will change with your unit size, floor and final agreement value.

Stage % Due Work Milestone on Site 2 BHK (₹1.62 Cr) 3 BHK (₹2.50 Cr) 4 BHK (₹3.60 Cr)
1 10% Booking amount to fix your unit ₹16.2 lakh ₹25 lakh ₹36 lakh
2 10% Agreement of Sale and land clearing ₹16.2 lakh ₹25 lakh ₹36 lakh
3 10% Deep site excavation complete ₹16.2 lakh ₹25 lakh ₹36 lakh
4 10% Foundation and plinth complete ₹16.2 lakh ₹25 lakh ₹36 lakh
5 10% Basement slabs complete ₹16.2 lakh ₹25 lakh ₹36 lakh
6 10% Ground floor slab complete ₹16.2 lakh ₹25 lakh ₹36 lakh
7 10% Upper floor superstructure complete ₹16.2 lakh ₹25 lakh ₹36 lakh
8 10% Internal walls and plastering complete ₹16.2 lakh ₹25 lakh ₹36 lakh
9 10% Internal MEP and plumbing complete ₹16.2 lakh ₹25 lakh ₹36 lakh
10 10% Occupancy Certificate and handover ₹16.2 lakh ₹25 lakh ₹36 lakh
Total 100% Possession by December 2031 ₹1.62 Cr ₹2.50 Cr ₹3.60 Cr

The build timeline runs around 57 months, so these ten payments spread over nearly five years. That gap gives you time to plan each instalment instead of arranging a large sum at once.

How the Booking and Agreement Stages Work


The first two stages need the most planning, because together they make up 20% of the price. Section 13 of the RERA Act stops a developer from taking over 10% before a registered sale agreement. So the booking amount stays capped at 10%, and the second 10% comes only after the agreement.

You also pay stamp duty and registration when you register the Agreement of Sale. So stage 2 becomes the heaviest cash month of the plan, and you should keep funds ready early.

Costs Outside the Payment Plan


The 10 instalments cover the agreement value only. Government and project charges sit on top, so add them to your budget from day one.

Charge Rate in Thane Example on a ₹2.50 Cr 3 BHK
Stamp duty (male buyer) 7% (5% duty, 1% metro cess, 1% LBT) ₹17.5 lakh
Stamp duty (female or joint buyer) 6% ₹15 lakh
Registration fee ₹30,000 flat for homes above ₹30 lakh ₹30,000
GST on under-construction homes 5% without input tax credit Up to ₹12.5 lakh

GST applies to each instalment you pay before the Occupancy Certificate, so it runs with most stages. Stamp duty uses the higher of your agreement value or the government's ready reckoner rate for the area.

Also ask the sales team about the maintenance deposit, club membership, car parking and floor rise charges. The developer has not yet published a full cost sheet, since the project is still in pre-launch.

How to Fund the Plan with a Home Loan


Most buyers combine their own savings with a home loan. RBI rules let banks fund up to 75% of the property value for loans above ₹75 lakh. So on a ₹2.50 Cr home, you need at least ₹62.5 lakh from your own savings.

Many buyers pay the first two stages from savings and let the bank cover later milestones. The bank then releases money directly to the developer as each stage completes on site.

During construction, you can choose between two repayment options:

  • Pre-EMI means you pay only interest on the amount the bank has released so far. Your monthly outgo stays low, but your principal does not reduce until full EMIs begin.
  • Full EMI means you start paying interest and principal from the first disbursement. Your monthly payment is higher, yet you save on total interest across the loan term.

If you already pay rent, pre-EMI keeps your cash flow easier. If your income allows it, full EMI brings your loan closure date forward.

Why a Construction-Linked Plan Suits This Project


A CLP ties your money to real progress, which matters for a large 15-acre project with nine towers. You can visit the site, see the slab or plaster work, and then release the next instalment. This keeps both risk and pressure lower than a heavy down payment plan.

Prestige Group also brings 40+ years of experience and 300+ delivered projects, backed by a CRISIL DA1+ rating. That track record adds confidence for buyers who plan to pay across nearly five years. For NRI buyers, a milestone-based schedule makes it easier to plan transfers from abroad in advance.

CLP vs Down Payment Plan: Quick Comparison


Some developers in the Mumbai region also offer a down payment plan with a discount for early payment. The table below shows how the two options differ for a buyer.

Factor Construction-Linked Plan (CLP) Down Payment Plan
Upfront payment 10% at booking, 10% at agreement Often 80% to 95% within a few months
Link to site progress Every payment follows a milestone Most money leaves before work starts
Price discount Usually none A small discount for early payment
Delay risk for you Lower, since unpaid stages stay with you Higher, since the developer holds your money
Home loan use Stage-wise disbursement Large disbursement at the start

For a pre-launch project with a five-year build cycle, the CLP keeps more control in your hands. If a down payment option comes up at launch, weigh the discount against the interest you would lose.

You can compare current rates for each configuration on the Prestige Falcon City Thane price page. To match your budget with a layout, check sizes on the floor plans page.

What to Check Before You Pay the Booking Amount


The project is in pre-launch, and its RERA registration is still in process. Payment terms can change before launch, so confirm these points with the sales team in writing:

  • Ask for the RERA registration number and the final payment schedule before you transfer any money.
  • Confirm whether the booking amount is refundable if you cancel before signing the agreement.
  • Request a full cost sheet with GST, parking, clubhouse and maintenance charges listed separately.
  • Check whether early buyers get a price benefit during the Expression of Interest (EOI) stage.
  • Ask which banks have approved the project, so your loan moves quickly after the agreement.

FAQs


1. What is the payment plan for Prestige Falcon City Thane?

The project follows a 10:10:80 construction-linked plan with 10 equal instalments. You pay 10% at booking, 10% at the sale agreement, and 80% across eight site milestones.

2. What is the booking amount at Prestige Falcon City Thane?

The booking amount is 10% of the agreement value. For a 2 BHK starting at ₹1.62 Cr, that comes to about ₹16.2 lakh. The amount rises with unit size.

3. How many instalments does the payment plan have?

The plan has 10 instalments of 10% each. The first two cover booking and the agreement, while the other eight follow work on site.

4. Do I pay GST on each instalment?

Yes, 5% GST applies to instalments you pay before the Occupancy Certificate. Once the developer receives the certificate, completed homes fall outside GST.

5. Can I use a home loan for the construction-linked plan?

Yes, banks disburse the loan in stages as each milestone completes. For loans above ₹75 lakh, banks fund up to 75% of the value, and you pay the rest.

6. When is the final payment due?

The final 10% falls due when the developer receives the Occupancy Certificate and prepares handover. The developer currently targets possession by December 2031.

Enquiry
Enquire Now